Public liability insurance for caravan owners: why it matters
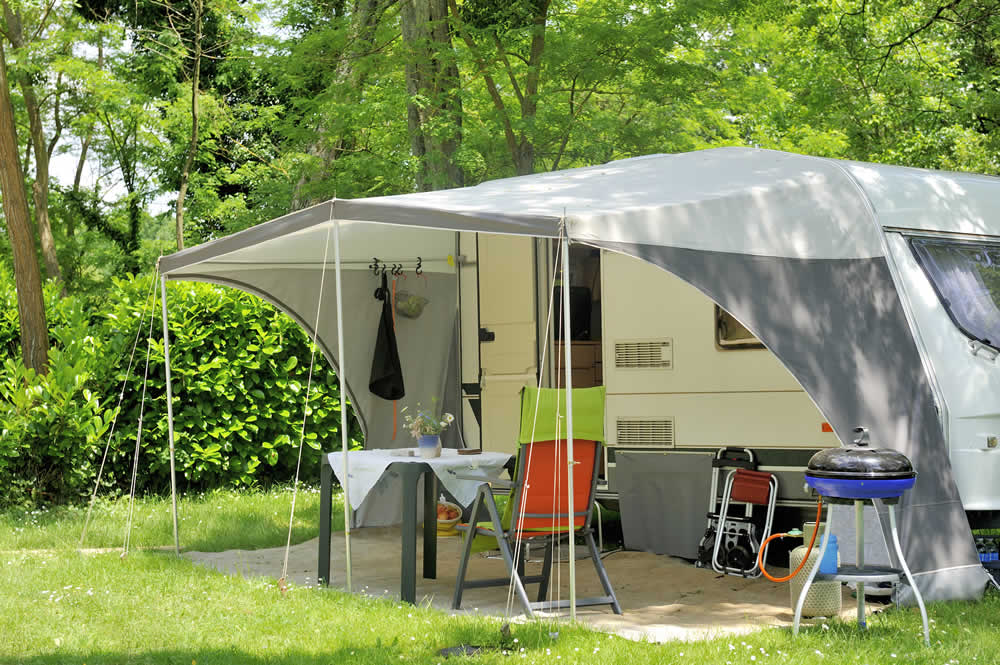
Caravan public liability insurance can protect you financially if someone is accidentally injured or their property is damaged and you are legally liable as a result of owning or using your caravan.
Whether you own a static caravan or a touring caravan, liability claims can potentially involve compensation and legal costs. Public liability cover can therefore be an important part of your caravan insurance.
The precise cover, limits, conditions and exclusions will depend on your individual policy.
What is caravan public liability insurance?
Caravan public liability insurance provides protection against certain claims made by third parties when you are legally responsible for accidental injury, death or damage to their property arising from your ownership or use of the caravan.
For example, depending on the circumstances and policy terms, a claim might arise if a visitor is injured in an accident associated with your caravan or if you accidentally cause damage to someone else’s property.
Liability claims can potentially involve both compensation and associated legal costs, which is why public liability can be an important element of caravan insurance.
Public liability insurance does not, however, cover every accident simply because it happens in or around your caravan. Any claim will be subject to the terms, conditions, limits and exclusions of the policy.
Do static caravan owners need public liability insurance?
Static caravan owners can face potential liability risks because family, friends and, in some cases, paying guests may spend time in and around the holiday home.
A visitor might be injured following an accident associated with the caravan, for example, or neighbouring property might be accidentally damaged.
Holiday parks may also require caravan owners to have a specified level of third-party liability insurance as part of their pitch agreement.
Cover4Caravans’ static caravan insurance includes liability cover.
If you let your static caravan to paying guests, it is particularly important to make sure your insurance reflects how the caravan is being used. Don’t assume that insurance arranged solely for private holiday use will automatically provide the protection you need when letting your caravan to other people.
Tell your insurer how you use the caravan and check the relevant policy documentation.
Do touring caravan owners need public liability insurance?
Touring caravan owners face a different range of potential liability risks because their caravans are moved between locations and used on different sites.
Once your caravan is pitched, an accident could potentially result in another person being injured or their property being damaged.
Cover4Caravans’ touring caravan insurance includes public liability among the types of cover available.
What happens to public liability cover while towing a caravan?
There is an important distinction when your caravan is being towed.
Public liability arising while towing is typically excluded from touring caravan insurance, as third-party liability would usually be covered by the towing vehicle’s motor insurance.
Cover varies between policies, however, so check both your caravan and motor insurance documentation to understand which policy applies in different circumstances.
It is also important not to assume that third-party liability cover provided by your motor insurance means the caravan itself is insured against accidental damage while being towed. Check the relevant policies to understand exactly what protection you have.
Does caravan insurance automatically include public liability cover?
Not necessarily. Caravan insurance policies and the protection they provide vary between insurers.
When comparing caravan insurance, check:
- whether public liability insurance is included;
- the maximum amount of liability cover;
- the circumstances in which the cover applies;
- any relevant exclusions; and
- whether the policy is suitable for how you use your caravan.
The last point can be particularly important if you let a static caravan to holidaymakers or if the way you use your caravan changes after you take out your insurance.
What does caravan public liability insurance cover?
The precise protection depends on the individual policy, but caravan public liability insurance may cover certain amounts you become legally liable to pay following accidental:
- bodily injury to another person;
- death of another person; or
- damage to another person’s property.
Cover may also extend to certain associated legal costs, depending on the policy.
Always check the policy wording rather than assuming a particular event or claim will be covered.
Why does caravan public liability insurance matter?
Most caravan holidays pass without incident, but accidents can happen.
If someone is injured or their property is damaged and you are found legally liable, a claim could potentially involve substantial costs.
Public liability insurance provides protection against specified liabilities, subject to the terms of the policy, rather than leaving you to meet an eligible claim yourself.
It is therefore worth looking beyond insurance for theft or accidental damage to the caravan itself when choosing cover. Understanding the public liability protection provided can be just as important.
Caravan public liability insurance FAQs
Is public liability insurance a legal requirement for caravan owners?
There is no general requirement for every caravan owner to have public liability insurance simply because they own a caravan. However, a holiday park or site may require a particular level of liability cover as part of its terms or pitch agreement.
Does public liability insurance cover my caravan?
Public liability insurance is designed to protect against specified liabilities to third parties. Cover for loss of or damage to your own caravan is a separate element of caravan insurance and will depend on your policy.
Does caravan public liability insurance cover paying guests?
This depends on the policy. If you let your static caravan to paying guests, tell your insurer and make sure the policy provides appropriate cover for how the caravan is being used.
Does caravan public liability insurance cover towing?
Public liability arising while a touring caravan is being towed is typically excluded from caravan insurance, as third-party liability would usually be covered by the towing vehicle’s motor insurance. Check both policies to establish the cover that applies.
Checking your caravan liability cover
Whether you own a touring caravan or static holiday home, check the level of public liability insurance provided and the conditions and exclusions that apply.
You can find out more in our caravan insurance guide or explore Cover4Caravans’ touring caravan insurance and static caravan insurance options.
This article is for general information only and does not constitute legal or insurance advice. Cover, limits, conditions and exclusions vary between policies, so always check the relevant policy documentation
Caravan news October 2026: new 2027 models, NEC show and park awards

Autumn may be here, but the touring caravan world is already looking ahead to 2027. From new models from Swift and Bailey to the October NEC show and award-winning caravan parks in Wales, here’s a round-up of some of the latest UK caravan news.
What’s new from Swift for the 2027 touring caravan season?
As the 2026 touring season winds down, manufacturers are already unveiling their 2027 ranges. Swift’s 2027 touring caravan collection includes updates across Sprite, Challenger, Conqueror and Elegance Grande, with 26 layouts across the ranges.
Highlights include:
Conqueror
- a new Conqueror 565 for 2027, with twin fixed single beds and a four-berth layout suited to couples or families;
- the layout combines a front lounge and L-shaped kitchen with fixed single beds and a rear washroom;
- standard features include Alde radiator central heating and water heating, a 120W roof-mounted solar panel, an external barbecue point and a solid-surface kitchen worktop.
Elegance Grande
- Swift’s flagship Elegance Grande range focuses on space, comfort and premium specification;
- the four 2027 models are 8ft wide and include Alde radiator central heating, Alde Flow continuous hot water and underfloor heating, onboard 4G Wi-Fi and wireless charging.
Sprite
- the Sprite range continues to focus on practicality and accessible touring;
- new for 2027 is the Sprite Grande Quattro FB – an 8ft-wide, six-berth, twin-axle model designed to offer more space for larger families.
Challenger
- the Challenger and Challenger Grande ranges combine practical layouts with a higher level of specification and comfort;
- features include Truma CombiNeo heating and hot water, a 120W roof-mounted solar panel, an external barbecue point and wireless charging.
The Motorhome & Caravan Show – October 2026
The annual Motorhome & Caravan Show returns to the National Exhibition Centre (NEC) in Birmingham from 13 to 18 October 2026, opening from 10am to 6pm each day.
The show is billed by the organiser as the UK’s biggest leisure vehicle showcase, bringing together hundreds of exhibitors and a wide range of new caravans, motorhomes, campervans, accessories and touring products across the NEC.
Award success for family-run caravan parks in Ceredigion
A family-run caravan park business in Ceredigion is celebrating a string of awards across two sites, according to a Cambrian News report published on 17 September 2026.
Wern Mill Caravan Park, run by Gwawr and Ifan Evans, Ywain Evans and Lucy Davies, has collected several accolades. These include recognition in the Welsh Enterprise Awards, a Tripadvisor Travellers’ Choice Award and an award from Campsites.co.uk.
The family also opened Llanina Caravan Park in March 2026. The site has since achieved a five-star grading from Visit Wales.
Bailey launches its new Unicorn family for 2027
British caravan manufacturer Bailey of Bristol has also unveiled its 2027 models, announcing the new Unicorn Family in a press release dated 24 September 2026.
The seventh-generation Unicorn Family now comprises three ranges – Lite, Deluxe and Grande – with 11 layouts designed around different touring requirements.
Each range offers a different balance of space, towing practicality, comfort and specification, giving buyers a wider choice within the established Unicorn line-up.
Taking your tourer to Germany: need to know
A touring caravan gives you the freedom of the open road – and if that road starts the moment you drive off a cross-Channel ferry or the Eurotunnel, the open road winds all over Europe.
Recent years have seen the widespread standardisation of rules of the road throughout much of the Continent. Even with the UK’s withdrawal from the EU – Brexit – that remains largely true but local and regional variations may still apply, depending on the country through which you are driving. So, don’t be one of those to be caught off-guard by the differences.
Since it is a great destination for British caravanners – not least because of the accessibility of its free-to-use motorway network and the high standards of its campsites – let’s look at some of the things you need to know about taking your touring caravan to Germany.
Documentation and equipment
In practice, you will find that very little has changed. The AA has published a checklist of documents and equipment you need to carry with you when towing a caravan in Europe. A quick review highlights that:
- you must hold a valid UK driving licence and be at least 18 years of age. If you hold a UK photocard driving licence, an International Driving Permit is not normally required when visiting Germany;
- you do not need to carry a green card when driving in Germany, although you must still have valid vehicle insurance. Check with your insurer that you have the appropriate cover for your vehicle and caravan while travelling in Europe;
- although separate touring caravan insurance is not a legal requirement, you’ll need appropriate cover if you want to protect your caravan against risks such as accidental damage, fire and theft. Check with your caravan insurance provider that your cover remains valid while travelling in Europe;
- take the original V5C registration document for your towing vehicle. If the vehicle is hired or leased, make sure you have the appropriate documentation confirming that you’re permitted to take it abroad;
- caravans and other trailers weighing more than 750kg must currently be registered before being towed to or through Germany. You can check the trailer registration requirements here;
- make sure your towing vehicle displays the UK identifier where required. GB stickers are no longer valid. If your number plate already displays the UK identifier together with the Union flag, you do not normally need a separate UK sticker when driving in Germany; and
- check whether the headlights on your towing vehicle need adjusting or headlamp converters for driving on the right.
Driving through France to get to your destination?
Unlike many other European countries, German rules recommend but, do not make compulsory, that you carry onboard an accident or emergency warning triangle, reflective jacket, first aid kit or fire extinguisher – or, for that matter, the breathalyser that is required in France.
But, if you are driving through France and Belgium (for example, from the Eurotunnel) then you must make sure you have the correct equipment and documentation.
Tolls and low-emission zones in Germany
If you have had to fiddle with change to pay the tolls on many motorways in France, Italy or Austria, it will come as a welcome surprise that Germany’s autobahns are generally toll-free for cars and caravans.
Beware that you may face on-the-spot fines for some motoring offences, however, and do not be tempted to use radar detection devices – they are illegal in Germany.
Germany also has low-emission zones (Umweltzonen) in a number of towns and cities. If you are planning to drive into one of these areas, your towing vehicle may need to meet the required emissions standard and display an environmental sticker (Umweltplakette) on the windscreen. The rules also apply to foreign-registered vehicles.
Low-emission zones are signposted, but it is worth checking your route before travelling, particularly if your campsite or sightseeing plans take you into or through a city. Driving into an environmental zone without the appropriate sticker can result in a fine.
You can find further information about environmental zones and other driving requirements in the GOV.UK travel advice for Germany.
Summary
We hope this brief blog is useful. If you are going to Germany, please do check the official websites for the latest documentation, towing and driving requirements as these may change.
For further information and destination ideas, please read our Guide to caravanning in Germany.
Top caravan holiday tips
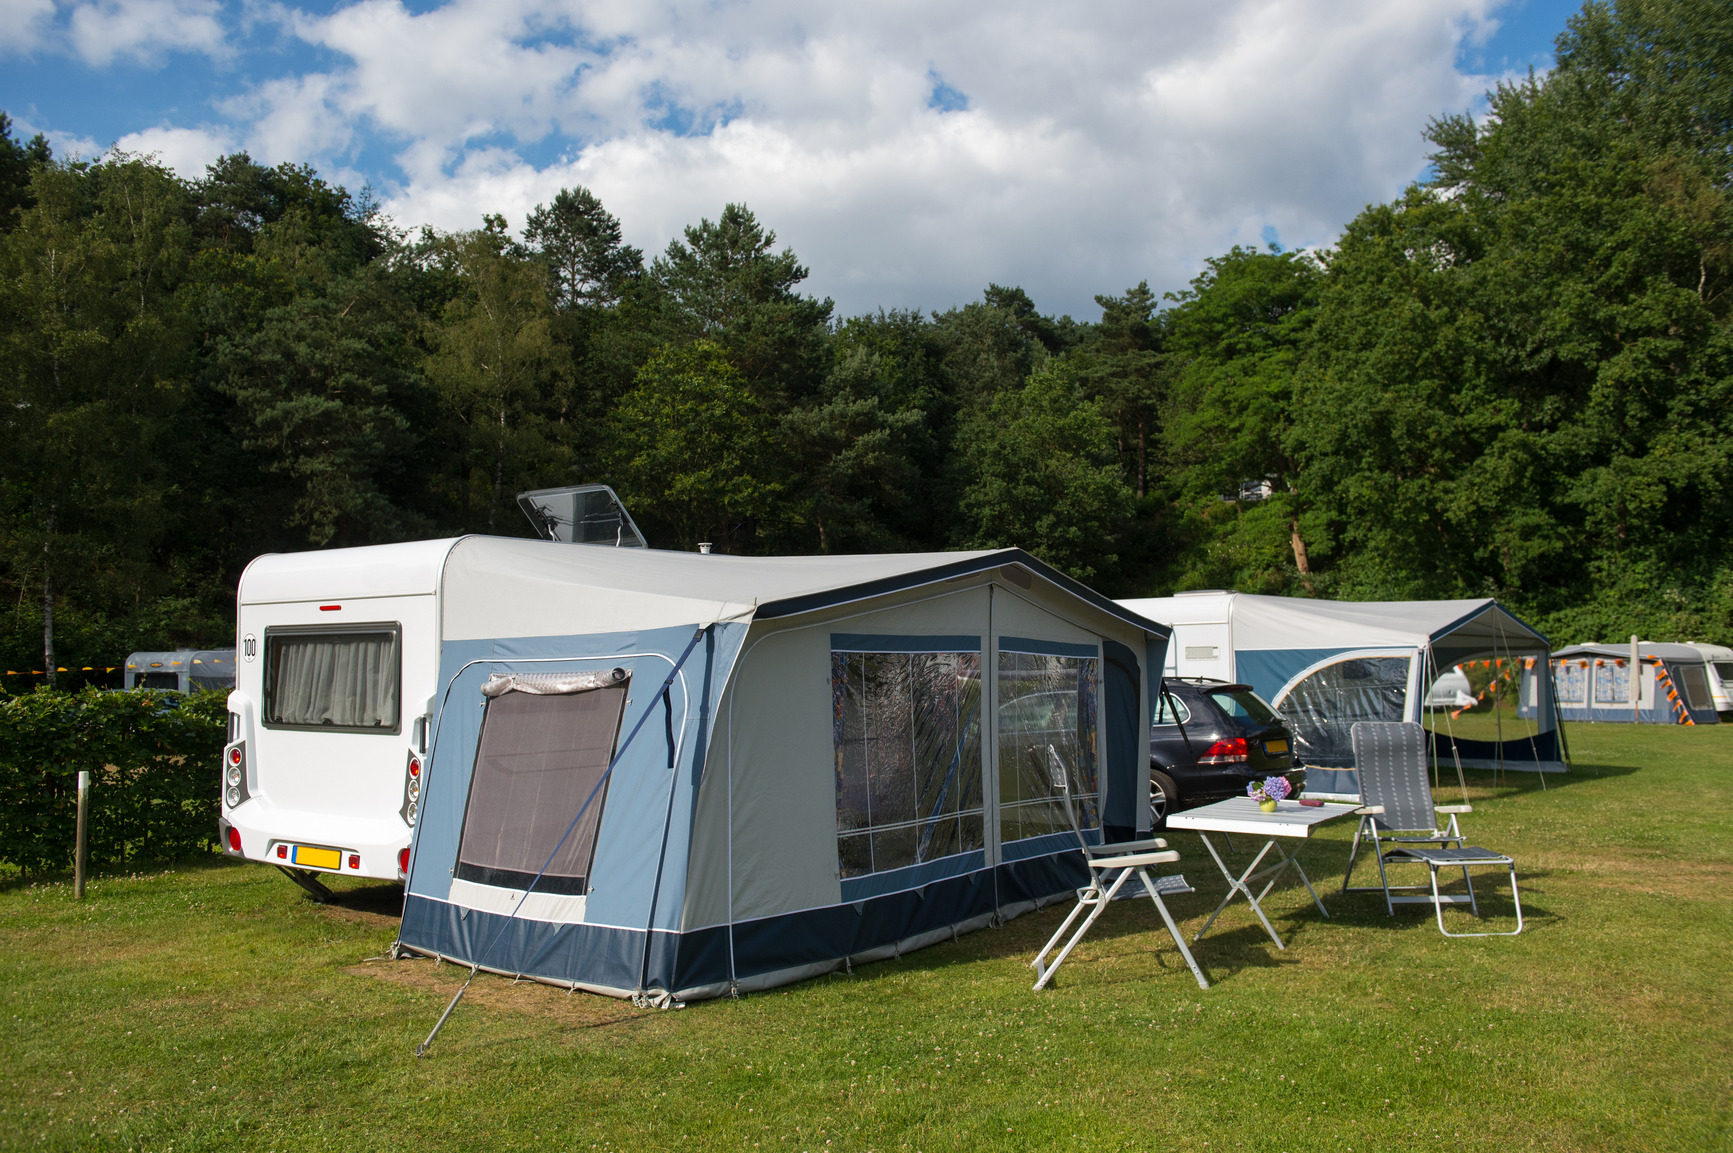
If you have never tried caravanning before or just bought your first one, you might be surprised by just how smooth, calm and hassle-free getting on the road, pitching up at your chosen caravan site and enjoying your holiday can be.
Some people might get into a proper lather running around to pack all the gear at the last minute and worrying about whether everything has been properly and safely packed. You, on the other hand, may be able to avoid all that simply by following a few of our caravan holiday tips:
Getting organised
- perhaps the biggest single key to hassle-free caravanning is simply being properly organised;
- it needn’t be as dry and boring as it sounds – planning what to pack, where to go, and researching the sites to choose from for your holiday is all part of the fun and excitement, so enjoy it;
- don’t forget, if you are planning to visit a new caravan site, why not visit our dedicated YouTube channel? We have lots of useful site arrival videos that show you how to get to your chosen campsite. Or simply browse this site for ideas.
Be prepared
- of course, you don’t want to start imagining all the things that might go wrong before you even leave home for your holidays, but there is still a lot to be said for being prepared;
- that means being prepared if something does go wrong and your caravan is damaged – or even stolen;
- that is when you may need the type of caravan insurance we arrange here at Cover4Caravans;
Towing courses
- although you are likely to get the hang of towing a caravan fairly quickly, if you are new to the skills required, you might want to take a towing course;
- practice in a controlled environment is likely to build your confidence when manoeuvring your caravan both on the road and when getting onto your pitch at the campsite – so taking any stress out of the experience;
- caravan mirrors can prove vital to safely towing and manoeuvring your caravan – to boost your confidence in the use of mirrors, you might want to review our detailed guide on the subject;
The master list
- even when you have become a seasoned hand, there is still much to be said for a master list of essential things and pieces of kit to remember to pack;
- you might add or take away from it over time, of course, but such a list might reduce the number of times you are left kicking yourself for something you forgot and left at home;
- you might want to start off your own master list by reviewing the Caravanning Checklist we’ve already prepared;
Hitchlocks and wheel clamps
Don’t forget to stow your hitchlock and wheel clamps – their use is likely to be a condition of your caravan insurance, both when you leave it unattended whilst still attached to your car (hitchlock and wheel clamps) and when it is unhitched and on your pitch at the campsite (wheel clamps alone).
Caravanning with children
Being prepared also means making special provision for any children that are holidaying with you – taking into account their ages and tastes, of course. Here are some tips …
- while a touring caravan lets you see many different places in one trip – so that no one gets bored – there is always the worry that you will not be able to keep them amused, especially if the notoriously unpredictable British weather turns inclement;
- although you will be hoping for dry weather, of course, always prepare for rain and pack some rainy-day activities such as board games, cards and the like to keep the youngsters occupied – we have a specially prepared Guide to what to do on rainy days which may help you plan;
- the drive itself can prove especially trying so have plenty of distracting entertainment to hand to head off any boredom – books, audiobooks, a games console, or any number of games you’ve pre-downloaded on a laptop;
- if it’s going to be an especially long journey, you could also find out if there are any places to stop off at on the way and break the journey up into shorter chunks – in addition to the regular comfort breaks, of course;
- take an “emergency” pack of non-perishable food and drink, plus hand wipes for those sticky fingers;
- careful planning is key to a successful holiday, so make sure you choose a suitable site to stay at;
- if you can find a site with a playground, shop, clubs and other child-friendly amenities, this could help the children (and you!) enjoy a better time – you can find out more about family sites in the UK at the Caravan and Motorhome Club website;
- if young children are with you, a good supply of games is essential when you go camping – so, pack a bat and ball, tennis rackets, a swingball set, a volleyball set, a frisbee and, if you have space, even some bikes;
- you will also need to keep all these games somewhere, so this could be a good time to invest in a large awning – just make sure you take security seriously because caravan insurance sometimes does not cover the contents of awnings if you do not take suitable security measures;
- whether or not you are travelling with children, you might want to select a caravan site located near some popular attractions so that you can spend time doing different things – if you choose a site near the beach or within striking distance of lots of walking trails, of course, you will always find something to do;
Caravan safety and first aid
- safety in your caravan is essential, of course, so you might want to review our comprehensive guide on the subject;
- important components of your safety equipment are the first aid kits designed not just for you but also for your caravan;
- in the first instance, you are likely to know already what first aid supplies you and your family may need;
- the “first aid kit” for your caravan might include items such as a torch (with fully-charged batteries and which you know works), an adjustable spanner, two screwdrivers (which might also be used as levers), spare fuses for the electrics and a can of WD40;
Overloading
- one of the reasons for giving careful thought about what to pack and what not to pack is to avoid the temptation to overload your caravan;
- as a rule of thumb, aim for the caravan’s fully laden weight (MTPLM) to be no more than 85% of the kerbweight of your towing vehicle, particularly if you are new to towing. More experienced towers may go higher, but you should never exceed the car manufacturer’s stated towing limit or other applicable weight limits;
- in the early days, of course, it might be difficult judging these payloads, so you might want to find your nearest public weighbridge to test them out a few times;
Wired to alarm
- naturally, an intruder or anti-theft alarm is a helpful safety and security device to fit to your caravan – and your insurer will certainly thank you for it;
- the Camping and Caravanning Club has published a detailed article about the many security devices and equipment available on the market – all of which are designed to make it more difficult for any thief to make off with your caravan;
- the article mentions that sticky labels prominently displayed in the window or on the body of your caravan might announce the security measures and anti-intruder devices you’ve installed – but also notes that some tracker devices rely on the fact that they remain hidden and are unknown to any thief.
Further reading: What security measures do caravan insurers expect?
Getting prepared!
These are just some of our suggestions and ideas for getting ready for your outings and adventures in your touring caravan.
Remember that planning is everything, so think carefully about every aspect of your adventure – from the fun of packing what you’ll need to safely arriving at the caravan site of your choice. If you are travelling with children, of course, you’ll want to keep them happily occupied for the long journeys as well as when you arrive at the site.
A little preparation before you set off can help take much of the stress out of your journey, leaving you free to enjoy your caravan holiday.
You may be interested in:
- Why planning matters more than people expect when touring with a caravan
- Guide to caravanning with pets
- Looking for destination inspiration? Then click here or check out our bespoke Trip related guides.
How to value a static caravan for insurance purposes

How much is your static caravan worth? It sounds like a straightforward question, but when you are arranging insurance, the answer is not necessarily the price you originally paid for it.
Getting your static caravan insurance value (the “sum insured”) correct matters because the figure may affect the amount of cover you have if something goes seriously wrong. So, where do you start?
What value should I insure my static caravan for?
First, check your insurance policy to see how your caravan is covered. Depending on the policy, this may be on a market value or new-for-old basis.
That distinction matters.
Market value generally reflects what a caravan of a similar make, model, age, specification and condition is worth at the relevant time.
New-for-old cover works differently. Subject to the terms and eligibility requirements of the policy, it is intended to provide for a new equivalent or comparable replacement following an insured total loss.
So, don’t automatically use the price you paid for your caravan several years ago. Equally, don’t simply pick a figure that seems about right. Check what your insurance provider or broker requires you to include in the value.
Don’t automatically use the price you paid
The purchase price is a useful reference point, but it isn’t necessarily the correct figure for insurance purposes.
That’s because the amount you paid may include costs that don’t form part of the caravan’s insured value. Depending on how and where you bought it, these might include:
- site or pitch-related charges;
- dealer or sales commission;
- finance charges;
- administration fees;
- service or maintenance packages;
- furniture or other optional extras; and
- other benefits included as part of the purchase.
There can be an issue in the other direction, too. The purchase price might not reflect some of the costs associated with replacing a caravan following a total loss. Depending on the circumstances and your policy, these could include removing and disposing of the damaged caravan, transporting a replacement and siting it on the pitch.
If possible, ask the park operator or dealer for an itemised breakdown of the purchase price. This may help separate the value of the caravan itself from site-related charges, services and optional extras.
Most importantly, check how your insurer wants the caravan valued and which costs need to be taken into account.
How can I find out what my static caravan is worth?
If you need to establish its current value, gather some basic information first. Note the manufacturer, model, age, dimensions, specification and general condition.
You can then look at similar caravans currently for sale. Caravan dealers, manufacturers and advertisements for comparable models can all provide useful pointers.
Try to compare like with like. A newer model, different specification or caravan in significantly better condition won’t necessarily provide a useful comparison.
And remember that an advertised selling price is just that – an asking price. It doesn’t necessarily tell you what the caravan will eventually sell for.
If you are struggling to arrive at a realistic figure, a professional valuation may be worth considering. Your insurer should also be able to explain the basis on which they expect the caravan to be valued.
What should I consider when calculating the insured value?
There isn’t a single calculation that applies to every static caravan insurance policy. What needs to be included will depend on the basis of cover and how your insurer defines the caravan, contents and other insured property.
There are, however, several things worth checking.
The caravan itself
Depending on your policy, the starting point might be the caravan’s current market value or the cost of replacing it with a new equivalent or comparable model.
When researching its value, make a note of the:
- make and model;
- year of manufacture;
- dimensions;
- number of bedrooms;
- specification;
- condition; and
- any permanent upgrades or improvements.
Purchase documents, photographs and an appropriate dealer or professional valuation can all be useful when establishing and recording the value.
Fixed fixtures, fittings and improvements
Think about what has been added to the caravan since it was manufactured or purchased.
This could include fitted furniture, integrated appliances, heating or air-conditioning systems, satellite equipment, accessibility adaptations and upgraded kitchens or bathrooms.
Don’t simply add the cost of everything to the caravan’s insured value, though. Your policy may treat some items as part of the caravan, others as contents, and some may be subject to separate limits or exclusions.
Contents
Furniture, televisions, kitchen equipment and other belongings can soon add up.
Check how your policy defines contents, what is included and whether any individual or overall limits apply. This is particularly important if you’ve replaced or added items since you first arranged your insurance.
Removal, disposal and re-siting costs
A total loss doesn’t necessarily end with the cost of buying another caravan.
The damaged caravan might need to be made safe, dismantled, removed from the pitch and disposed of. There may be debris-clearance costs, while a replacement caravan may need to be transported to the park and sited.
These costs can be significant, but don’t assume they need to be added to your sum insured. Some policies may cover certain removal, debris-clearance, delivery or re-siting costs separately or subject to specific limits.
Check your policy wording or ask your insurer whether these expenses are covered and, importantly, whether any of them need to be allowed for when calculating your static caravan insurance value.
Why does an accurate static caravan insurance value matter?
Underestimating the amount you need could leave you without sufficient insurance to meet the full cost of an insured loss. Your policy may also contain specific provisions dealing with underinsurance.
When should I check the value again?
A good time to review your static caravan insurance value is at renewal.
Don’t just carry forward last year’s figure without thinking about it. Caravan values and replacement costs can change, and you may have made improvements or added equipment since you originally arranged the insurance.
Keep photographs, purchase documents, receipts for significant additions and any valuation documents somewhere safe. If you ever need to make a claim, having a record of your caravan, its specification and associated items may be useful.
What if I’m still not sure what value to use?
Ask your insurance broker.
They can explain whether your policy uses market value, new-for-old or another basis of settlement, what should be included and how associated costs and additions are treated.
It is far better to clarify your static caravan insurance value when arranging or renewing your cover than to discover after a loss that you and your insurer had different ideas about how the caravan should have been valued.
Please note: This article is for general information only and does not constitute insurance or valuation advice. Static caravan insurance policies vary between providers, including how caravans and associated items are valued and how claims are settled. Terms, conditions, exclusions and limits apply.